Tradingby Akhil Gaddam
Building Profitable Trading Systems: Backtesting, Forward Testing, and Live Trading Validation
3 min read24 February 202647 reads
Written by

1 follower
# Building Profitable Trading Systems: From Backtesting to Live Trading
## Introduction
Profitable traders don't trade hunches—they trade systems. A trading system is a set of rules that defines entries, exits, risk management, and position sizing. This guide teaches you to build, test, and validate systems that work in live markets.
## The Three Phases of Trading System Development
Phase 1: Backtesting - Validate rules on historical data
Phase 2: Forward Testing - Paper trade recent past on demo accounts
Phase 3: Live Trading - Small account with real money
Only advance after proving profitability in each phase.
## Backtesting Fundamentals
Backtesting Objectives:
- Identify realistic win rate and profit factor
- Detect curve-fitting (over-optimization)
- Calculate maximum drawdown
- Validate risk-reward ratios
- Find optimal position sizing
How to Backtest:
1. Define entry signals
2. Define exit signals
3. Set stop-loss distance
4. Set profit target distance
5. Apply position sizing rule
6. Test on 200+ trades minimum
7. Calculate key metrics
Key Metrics:
- Win Rate: % of winning trades (target: 50%+)
- Profit Factor: Gross profit / Gross loss (target: 1.5+)
- Drawdown: Largest peak-to-valley loss (limit: 20%)
- Avg Win/Loss Ratio: Average winner / average loser (target: 1.5+)
## Avoiding Curve-Fitting
What is Curve-Fitting?
Optimizing parameters so perfectly to historical data that the system fails on new data. Example: Tweaking moving average lengths until it matches past prices exactly.
How to Avoid It:
1. Use broad parameter ranges, not narrow ones
2. Out-of-sample testing: Test on different time periods
3. Walk-forward analysis: Test periods the system wasn't optimized for
4. Fewer parameters = less curve-fitting risk
5. Test parameter robustness: Change values by ±10% and verify performance still works
## Forward Testing: Paper Trading
What is Forward Testing?
Trading the system on demo accounts using recent real market data without risking capital.
Goals:
- Confirm backtest results match paper trading results
- Identify execution issues (slippage, fills)
- Build trader psychology confidence
- Find real-world problems
Duration: Trade 50+ paper trades minimum before considering live trading
## Live Trading: Risk Management
Start Small:
- Use 1-2% of capital on first account
- Limit daily losses to 5% max
- Never risk more than 2% per trade
- Keep detailed trade journal
Red Flags to Stop Trading:
- Win rate drops below 40%
- Profit factor drops below 1.2
- Consecutive losses exceed system drawdown
- Emotional trading vs. system trading
## Position Sizing Rules
Fixed Fractional:
- Risk 1% on every trade
- Example: $10,000 account = $100 risk per trade
Optimal f:
- Risk more on high-confidence trades
- Requires accurate expectancy calculations
- More advanced but higher returns
## Trade Journal Essentials
Track for every trade:
- Entry date/price/reason
- Exit date/price/reason
- Win/loss
- Trade size
- Emotional state
Review: Weekly win rate and profit factor vs. expectations
## Common System Development Mistakes
Mistake 1: Testing only bull markets
Mistake 2: Insufficient sample size (under 100 trades)
Mistake 3: Ignoring transaction costs
Mistake 4: Over-optimization on one asset
Mistake 5: Skipping forward testing phase
## Building Your First System
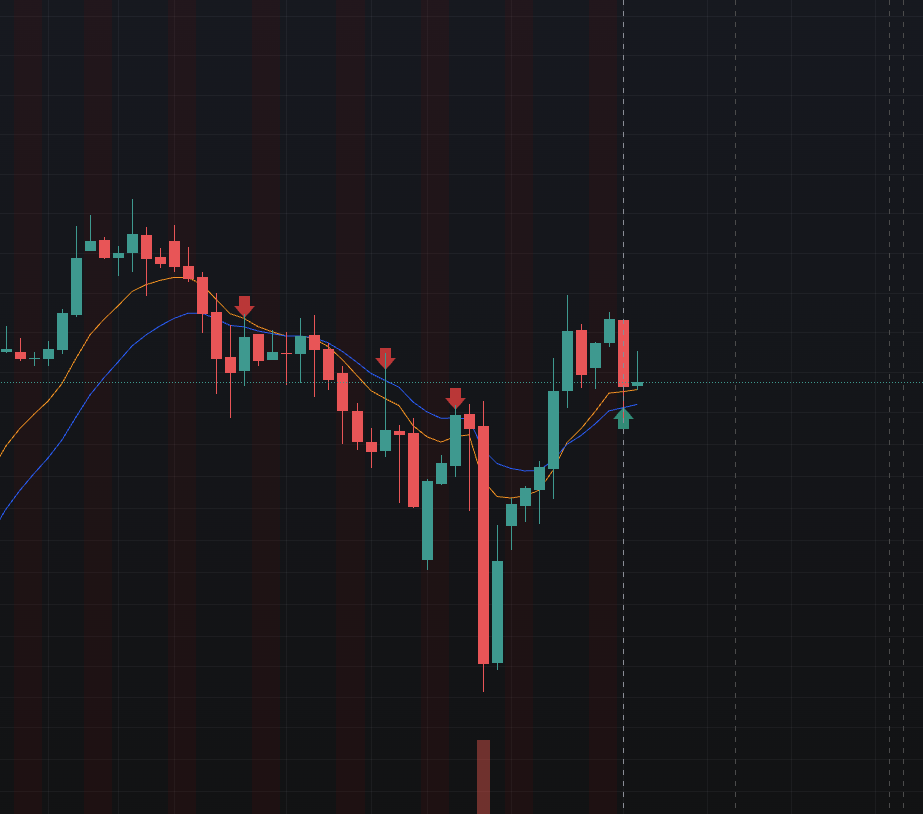
Simple System Template:
Entry:
- Price breaks above 20-period resistance
- RSI above 50
- Volume > 20-period average volume
Exit:
- First Target: +2% move
- Trail Stop: 1.5% below highest point
Stop Loss: 3% below entry
Position Size: 1% risk
Risk-Reward: 2:1 minimum
## Key Takeaways
- Systems remove emotion from trading
- Backtest minimum 200 trades before trading live
- Avoid curve-fitting through out-of-sample testing
- Forward test on paper before risking capital
- Start live with 1-2% of capital
- Track every trade in detailed journal
- Position size is critical risk management tool
- Most important: consistency over perfection
## Conclusion
Building profitable trading systems isn't complicated—it's methodical. Most traders fail because they trade emotion instead of executing systems. By backtesting rigorously, forward testing thoroughly, and starting live with proper risk controls, you join the professional minority. Your system doesn't need 80% win rate; it needs positive expectancy and consistent execution. That's how real wealth is built in trading.